

Blogs
PW Consulting: Industrial Temperature Controllers Market to Hit $3,132.63M by 2032, 4.6% CAGR
By PW Consulting, 2026-09-16
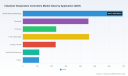
Navigating Precision: Strategic Insights for the Industrial Temperature Controllers Market in 2026
Executive Summary: The Case for Strategic Foresight
In the complex landscape of industrial automation, temperature control remains a foundational element of operational efficiency, product quality, and safety. As we move beyond the base year of 2025, enterprise leaders face a critical juncture. The trajectory of the Industrial Temperature Controllers Market is not merely a function of technological advancement but a reflection of broader macroeconomic shifts, regulatory pressures, and evolving manufacturing demands. Our latest comprehensive market study is designed to equip stakeholders with the granular intelligence necessary to navigate this evolving terrain.
This article serves as a strategic primer, outlining the scope, methodology, and competitive dynamics analyzed in our full report. While we highlight key market forces and structural trends here, the proprietary segmentation data, detailed revenue forecasts, and specific risk assessments contained within the complete publication remain exclusive to our subscribers. The objective is to demonstrate the depth of our analysis while underscoring the necessity of accessing the full intelligence package for actionable decision-making.
Market Trajectory and Growth Vectors
The historical performance of the industrial temperature control sector indicates a steady expansion, driven by the relentless need for precision in processing industries. Our analysis covers historical data spanning from 2020 through 2025, establishing a robust baseline for forecasting the period from 2026 to 2032. The market has demonstrated resilience and consistent upward momentum, reflecting the integral role of thermal management in modern industrial operations.
Looking forward, the forecast period anticipates continued growth, underpinned by a compound annual growth rate that signals sustained investment in automation technologies. This growth is not uniform across all vectors; it is propelled by specific technological shifts and regional industrialization efforts. Understanding the magnitude of this expansion requires a nuanced view of how different controller types and application sectors contribute to the overall revenue pool. While the aggregate market size figures point to a significant valuation by the end of the forecast period, the strategic value lies in dissecting the drivers behind these numbers.
Key growth vectors include the modernization of legacy manufacturing infrastructure and the adoption of smart control systems in emerging economies. However, capturing these opportunities requires more than top-line figures. It demands an understanding of the interplay between supply chain dynamics, component availability, and the specific thermal requirements of high-growth sectors such as energy and advanced manufacturing.
Irrigation Controllers Market
Competitive Landscape and Key Players
The market structure is characterized by a mixture of established global conglomerates and specialized regional players. Our report provides an in-depth profiling of key companies that are shaping the competitive environment. Understanding the strategic positioning of these entities is vital for companies looking to benchmark their performance or identify potential partnership opportunities.
Among the leaders, Omron Corporation stands out with a strong focus on PID process controllers. Their offerings are deeply integrated into industrial automation and manufacturing workflows, emphasizing precision regulation that aligns with high-standard automation protocols. Headquartered in Kyoto, Japan, Omron continues to leverage its global footprint to deliver solutions that cater to complex industrial requirements.
Similarly, Watlow Electric Manufacturing Company maintains a significant presence, particularly in the realm of precision temperature controllers and thermal management systems. Based in the United States, Watlow's portfolio extends to multi-loop process controllers, addressing applications where multiple thermal zones must be managed simultaneously. Their approach underscores the importance of reliability in harsh industrial environments.
On the other side of the spectrum, Yudian Temperature Control Technology Co., Ltd. represents a pivotal player in the global supply chain, headquartered in Xiamen, China. Yudian has distinguished itself not only through product volume but through regulatory and standards leadership. Notably, Yudian was the first in the instrumentation industry to achieve UL certification as of 2012, a milestone that opened doors to stringent international markets. Furthermore, the company has led the drafting of the core Chinese national standard GB/T 20819.1-2015 for Controllers with Analogue Signals for Industrial Process Control Systems. This involvement in standards setting signals a long-term commitment to compliance and interoperability. Their products are exported to over 150 countries and regions, highlighting their extensive global distribution network.
Additionally, Wuxi Keen Technology Co., Ltd. (Cakeen) is increasingly relevant, particularly for integrated PID temperature controllers and semiconductor-related heating solutions. Based in Wuxi, Jiangsu Province, their growth reflects the broader trend of specialized manufacturers catering to high-tech manufacturing needs where precise thermal control is critical for component integrity.
The competitive dynamics are further influenced by market concentration. Our analysis indicates a moderately concentrated market where top players hold significant share, creating both barriers to entry and opportunities for consolidation. Understanding the strategic moves of these key firms—from product launches to geographic expansion—is essential for anticipating market shifts.
Segmentation and Application Drivers
A core component of our research is the detailed breakdown of the market by type and application. The choice of controller technology often dictates the efficiency and cost-effectiveness of an industrial process. The market is segmented into categories such as On/Off Controllers, Proportional Controllers, and PID Controllers. Each category serves distinct operational needs, from simple heating tasks to complex, variable Process control loops requiring high precision.
In terms of application, the demand is spread across a diverse range of industries. Sectors such as Metals Mining & Metallurgy, Chemicals, and Food & Beverages represent significant consumption hubs due to the critical nature of temperature in material processing and safety compliance. Energy & Power and Oil & Gas also remain steady contributors, driven by infrastructure maintenance and operational safety requirements. General Manufacturing and other sectors provide additional volume, reflecting the ubiquitous need for thermal management across the industrial base.
While aggregate figures provide a view of total market size, the strategic insight lies in recognizing how these segments interact. For instance, the shift towards automation in food processing may drive demand for specific controller types that differ from those preferred in metallurgy. Our full report delves into these nuances, providing the specific revenue breakdowns and growth rates for each segment without the noise often found in generalized industry summaries.
Regional Dynamics and Market Concentration
Geographically, the market exhibits distinct characteristics influenced by local industrial policies, manufacturing capacity, and adoption rates of advanced automation. The analysis covers five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Industrial Temperature Controllers Market
Asia Pacific often emerges as a critical hub due to the density of manufacturing activity and rapid industrialization. However, mature markets in North America and Europe continue to drive demand through upgrades and replacements of existing infrastructure. Latin America and the Middle East and Africa present growth opportunities linked to resource extraction and energy sector developments.
Market concentration metrics suggest that while the market is accessible, scale and distribution networks play a crucial role in securing market share. Companies operating in this space must navigate varying regulatory environments and supply chain complexities unique to each region. Our report analyzes these regional disparities to help stakeholders identify where to focus their commercial efforts.
Regulatory and Compliance Influences
Regulatory frameworks and industry standards significantly impact product development and market access. Compliance is no longer optional; it is a competitive differentiator. As noted in our findings, certain manufacturers have moved early to secure certifications that facilitate international trade. For example, achieving UL certification can be a gateway to North American markets, while adherence to national standards like GB/T in China ensures domestic competitiveness and export compliance.
These regulatory milestones affect not only the manufacturers but also the end-users who require assurance of safety and reliability. In sectors like chemicals and energy, non-compliance can lead to severe operational risks. Therefore, our market study incorporates an analysis of how regulatory trends are shaping product specifications and procurement criteria. This includes tracking standards development and certification achievements that may alter the competitive balance.
Methodological Rigor and Data Integrity
To ensure the reliability of our insights, the report employs a multi-faceted research methodology. This includes extensive primary interviews with industry stakeholders, suppliers, and end-users, supplemented by secondary research from credible industry databases and financial reports. The data is validated through triangulation to minimize bias and ensure accuracy.
Our base year analysis establishes the current market state, while the forecast period utilizes trend analysis and modeling to project future performance. We account for variables such as economic fluctuations, technological disruptions, and supply chain constraints. This rigorous approach ensures that the insights provided are robust enough to support high-stakes strategic planning.
Strategic Value for 2026 Decision Makers
Why does this matter for your organization in 2026? In an environment where capital allocation must be precise, understanding the market trajectory of industrial temperature controllers can inform investment decisions, product development roadmaps, and supply chain strategies.
- Investment Planning: Identify high-growth segments before they become saturated.
- Competitive Benchmarking: Understand where key players are focusing their R&D and sales efforts.
- Risk Mitigation: Anticipate regulatory changes and supply chain disruptions that could impact operations.
- Market Entry Strategy: Evaluate regional potentials based on detailed demand analysis rather than generic assumptions.
The full report provides the specific data points required to execute these strategies. It moves beyond general trends to offer actionable intelligence on revenue potentials, market shares, and specific growth rates across all analyzed dimensions.
Conclusion: Accessing the Full Intelligence
The Industrial Temperature Controllers Market is poised for continued evolution, driven by technological refinement and industrial demand. However, navigating this landscape requires more than surface-level observations. It demands a deep dive into segmentation, competitive moves, and regional specifics.
This article has outlined the scope and strategic relevance of our latest study. To access the complete repository of data—including detailed segmentation revenues, specific CAGR breakdowns by segment, and comprehensive company profiles—we invite you to consult the full report. Equip your team with the precise intelligence needed to lead in 2026 and beyond. The future of industrial precision belongs to those who plan with data-driven confidence.
For detailed analysis of this topic, please visit the official page: Industrial Temperature Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pipe Joints Market Hits $228.6M in 2025, Projected to Reach $327.9M by 2032
By PW Consulting, 2026-09-16
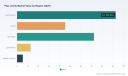
Strategic Intelligence for the Pipe Joints Market 2026-2032: Navigating Growth, Competition, and Regulatory Shifts
The global pipe joints market stands at a pivotal juncture as organizations prepare for the 2026 fiscal year and beyond. Infrastructure spending, industrial expansion, and evolving safety regulations are converging to reshape demand patterns across multiple sectors. For executives, procurement leaders, and strategic planners, the ability to anticipate these shifts is not merely an advantage, it is a necessity. Our latest Pipe Joints Market research delivers a comprehensive, data-driven blueprint designed to inform capital allocation, product positioning, and competitive strategy through 2032.
This insight briefing outlines the macro trajectory, competitive architecture, and emerging dynamics that will define the market landscape. It is structured to demonstrate the analytical rigor and actionable depth embedded in the full report, while intentionally reserving granular segmentation figures, regional breakdowns, and application-specific revenue allocations for the complete dataset available on our platform.
Macro Trajectory: A Resilient Growth Arc Across the Forecast Horizon
Drawing on historical performance from 2020 through 2025 and extending into a seven-year forecast period spanning 2026 to 2032, the market demonstrates a consistent upward trajectory. The overall revenue base, measured in USD millions, has progressed from 173.5 in 2020 to 181.33 in 2021, 187.78 in 2022, and 209.06 in 2023. The pace of expansion accelerated notably in 2024 and 2025, with recorded revenues of 209.42 and 228.6 respectively, reflecting stronger industrial activity, renewed construction momentum, and recovering supply chain conditions.
The forecast window projects sustained growth, with the market expected to reach 243.46 in 2026, followed by 255.59 in 2027, 269.9 in 2028, 290.04 in 2029, 293.41 in 2030, 308.93 in 2031, and a projected 327.9 by 2032. This pathway corresponds to a compound annual growth rate of 5.35 percent across the forecast horizon, signaling a market that is expanding at a steady, investable pace rather than experiencing volatile spikes. For strategic planners, this CAGR provides a reliable baseline for capacity planning, inventory forecasting, and long-term partnership structuring.
Importantly, the absolute scale of the market and the consistency of its growth underscore the foundational role that pipe joints and couplings play across critical infrastructure and industrial ecosystems. As organizations map their 2026 objectives, understanding how this trajectory aligns with regional development cycles, application-specific demand surges, and material cost normalization becomes a central component of scenario planning.
What the Report Delivers: Operational Content Designed for Execution
The full Pipe Joints Market study goes beyond top-line projections to equip decision-makers with structured, implementation-ready intelligence. The report is organized around several core analytical pillars, each calibrated to support distinct enterprise functions:
- Market sizing and forward modeling: Historical baselines and forecast pathways are presented with methodological transparency, enabling teams to anchor budgeting and demand planning in validated trajectories rather than speculative estimates.
- Segmentation architecture: The analysis dissects the market across product types, application verticals, and geographic regions. While aggregate growth signals are clear, the report provides the segmented context necessary to identify where demand is concentrating, which product categories are outpacing the broader curve, and how application-driven procurement patterns differ across industries.
- Competitive landscape and concentration metrics: Market structure is evaluated through concentration indicators, revealing the degree of fragmentation versus consolidation. This framework helps organizations assess entry barriers, partnership opportunities, and the strategic implications of operating in a market where the top three players hold a measured share and the top five maintain a slightly broader but still moderate footprint.
- Pricing and cost environment analysis: Unit economics are examined in the context of material inputs, manufacturing complexity, and specification tiers. The report situates price ranges for standard metal and alloy fittings within broader cost dynamics, giving procurement and pricing teams a reference frame for negotiations, margin planning, and make-versus-buy decisions.
- Regulatory and compliance mapping: Emerging codes and installation mandates are tracked to highlight how policy shifts influence material selection, approval workflows, and project timelines. This section is particularly relevant for firms operating in jurisdictions where nonmetallic joint specifications and manufacturer installation protocols are becoming more stringent.
- Recent industry developments and event intelligence: Product launches, trade show activity, and supplier announcements are synthesized to provide a live pulse on innovation cadence and market engagement. This ensures that strategy teams are aware of near-term product introductions and industry gatherings that may influence competitive positioning or procurement cycles.
Competitive Landscape: Key Players and the Structure of Market Participation
The pipe joints sector is characterized by a mix of established manufacturers, specialized engineering firms, and regional suppliers, each competing on dimensions such as joint integrity, installation efficiency, diameter range, and application-specific performance. The report profiles several core companies whose product portfolios and recent moves illustrate the competitive dynamics shaping the market.
Northwest Pipe Company, headquartered in Bellingham, Washington, focuses on engineered steel water pipe solutions with watertight joint systems, including its InfraShield® platform and custom mechanical couplings designed to preserve pipeline integrity under demanding service conditions. Victaulic, based in Easton, Pennsylvania, manufactures grooved mechanical pipe couplings and joining systems that emphasize faster, safer installation across industrial applications, and has continued to expand its fire protection portfolio with recent coupling introductions targeting rigid pipe joints in sprinkler systems. Teekay Couplings, operating from the United Kingdom, produces mechanical pipe couplings spanning a wide diameter range, with an emphasis on space, weight, and installation efficiency for diverse project requirements.
American Cast Iron Pipe Company, located in Birmingham, Alabama, offers restrained joint solutions such as Flex-Ring and Field Flex-Ring designs for ductile iron pipe, addressing endwise separation risks under thrust conditions. Holz Rubber Company, based in the United States, manufactures custom and standard expansion joints that absorb thermal movement and accommodate misalignment in piping systems, supporting reliability across variable operational environments.
These profiles are not isolated company snapshots; they are embedded within a broader concentration analysis that quantifies how market share is distributed and what that distribution implies for competitive strategy. In a market where the top three participants collectively hold approximately 22.8 percent and the top five reach roughly 28.5 percent, the landscape remains relatively fragmented at the top, leaving meaningful room for specialized players, regional specialists, and innovation-driven entrants to compete on performance, service, and application focus rather than scale alone.
Recent activity reinforces this dynamic. In early 2026, Victaulic introduced its style 009v FireLock coupling for rigid pipe joints in sprinkler systems, reflecting continued product development in fire protection and mechanical coupling segments. On the industry engagement front, Iran PIVEX held a January 2026 trade show featuring pipe joints and fittings from international suppliers, while the TUBE Trade Fair in Düsseldorf, scheduled for April 2026, is expected to showcase a broad array of pipe joints and coupling exhibitors. These events signal active supplier participation and sustained interest in cross-border sourcing, technology demonstration, and partnership formation.
Market Dynamics and Contextual Forces Shaping 2026 Decision-Making
Beyond sizing and competition, the research integrates the contextual forces that influence how the market behaves in practice. One notable development is the normalization of raw material costs. Steel prices for pipe joints and couplings are moderating in 2026 following earlier declines, as base metal costs stabilize. This shift has direct implications for manufacturing margins, supplier pricing strategies, and procurement timing, particularly for organizations that delayed purchasing decisions during periods of price volatility.
Pipe Joints Market
Artificial Joints Market
Regulatory evolution is equally consequential. The 2025 Ohio Fire Code mandates that nonmetallic pipe joints must be approved and installed in accordance with manufacturer instructions, reinforcing the importance of compliance documentation, approved product listings, and installer training. For firms operating in or supplying to jurisdictions with similar code trajectories, this type of requirement can affect product selection, project approval timelines, and the relative attractiveness of metallic versus nonmetallic joint solutions in specific applications.
Cost structures also vary meaningfully across specification tiers. General steel or metal pipe joints typically range from approximately USD 30 to over USD 200 per unit, while high-specification alloy fittings can reach between USD 500 and USD 2,000. These ranges illustrate how performance requirements, material grades, and application criticality drive pricing dispersion. For strategic planners, the key insight is that average market growth does not imply uniform profitability across all product categories; instead, value capture often depends on positioning within higher-specification segments, optimizing supply chain efficiency, or differentiating through installation reliability and joint performance.
Together, these dynamics create a market environment where growth is broad-based but execution is highly segmented. Companies that succeed in 2026 and beyond will be those that align their product portfolios with application demand, monitor material cost trends closely, and maintain agility in response to code changes and installation standards.
Why This Research Matters for 2026 Enterprise Decisions
As organizations finalize 2026 strategies, the pipe joints market presents both opportunity and complexity. The projected expansion from 243.46 in 2026 toward 327.9 by 2032, supported by a 5.35 percent CAGR, indicates that demand will continue to grow at a meaningful pace. however, growth at the aggregate level masks important variation across regions, product types, and end-use sectors. Without segmented visibility, companies risk overcommitting to underperforming categories, underestimating regional demand intensity, or misaligning pricing and inventory strategies with actual procurement behavior.
This research is designed to reduce that uncertainty. By combining macro forecasting with structured segmentation, competitive profiling, concentration metrics, and contextual intelligence on materials, regulation, and recent industry activity, the report provides a decision-ready framework for multiple functional teams:
- Strategy and corporate development: Evaluate where to invest, which application verticals offer the strongest near-term tailwinds, and how market concentration shapes partnership and acquisition logic.
- Sales and commercial leadership: Identify high-potential segments, tailor value propositions around joint integrity, installation efficiency, and compliance readiness, and align go-to-market plans with regional demand patterns.
- Procurement and supply chain: Time purchases in response to material cost normalization, assess supplier diversity and concentration risk, and benchmark unit economics against specification tiers.
- Product and engineering: Prioritize development toward mechanical coupling innovations, restrained joint technologies, expansion joint solutions, and fire protection systems where recent launches and trade show activity indicate active market interest.
The full report also contains the detailed regional and application-level segmentation data, granular revenue allocations, and deeper competitive benchmarking that are essential for precise planning. Those specifics are intentionally reserved for the complete dataset, ensuring that teams accessing the full study receive the uncompromised intelligence needed for targeted execution.
Looking Ahead: Positioning for Durable Advantage
The pipe joints market is not simply expanding; it is evolving in ways that reward precision, compliance awareness, and application-specific engineering. As steel costs stabilize, fire and installation codes tighten, and major suppliers continue to introduce specialized coupling and joint technologies, the competitive edge will belong to organizations that can translate market-level growth into segment-level action.
Our Pipe Joints Market research provides the foundation for that translation. It equips leadership with the historical context, forecast confidence, competitive structure, and dynamic intelligence required to make informed decisions throughout 2026 and across the remainder of the forecast period. For teams ready to move from high-level outlook to detailed planning, the complete report offers the segmentation depth, regional specificity, and application-level revenue context necessary to operationalize strategy with precision.
The 2026 market environment will reward those who prepare with data, act with segmentation discipline, and monitor the regulatory and material shifts that shape real-world demand. This study is built to support that preparation from the first strategic review through to execution.
For detailed analysis of this topic, please visit the official page: Pipe Joints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2035, the global patient lift accessories market is projected to show steady revenue growth. Starting at $1,590 Million in 2020, the market reached $2,180 Million in 2025, reflecting expanding hospital investments and increased homecare adoption. Continued technological innovation and emerging market penetration are expected to drive the market to approximately $4,260 Million by 2035.
Read More - https://bussinessinsights.com/research-report/global-patient-lift-accessories
Hospital applications constitute the largest slice of the global patient lift accessories market share in 2025, driven by stringent safety regulations and high patient turnover. Homecare is quickly catching up, thanks to the rise in aging-in-place trends. Rehabilitation centers and elderly care facilities also contribute steadily, with specialized accessories addressing unique mobility needs. This diverse split ensures steady market expansion and customization by leading suppliers.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-patient-lift-accessories
Frequently Asked Questions
Who are the key players in Global Patient Lift Accessories industry?
The top 5 players in the Global Patient Lift Accessories industry are Hill-Rom Holdings, Inc., Invacare Corporation, Arjo, Handicare Group AB, and GF Health Products, Inc. These companies are industry leaders, known for their innovative solutions, global presence, and comprehensive product portfolios that cater to hospitals, care homes, and residential settings.
What is the Global Patient Lift Accessories growth?
The Global Patient Lift Accessories market has shown steady growth, with factors like aging population and increased adoption of safe patient handling solutions. For example, Hill-Rom reported a surge in demand for patient handling products in 2023, contributing to market expansion and improved healthcare facility ergonomics.
Which segment accounted for the largest Global Patient Lift Accessories share?
The hospital segment accounted for the largest share of the Global Patient Lift Accessories market. Hospitals invest heavily in these accessories to enhance patient safety, minimize injury risks for caregivers, and comply with regulatory standards, leading to higher adoption of slings, spreader bars, and scales in clinical settings.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
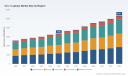
Strategic Intelligence for the 2-in-1 Laptop Market: Navigating Growth, Disruption, and Competitive Realignment in 2026
The 2-in-1 laptop category has evolved from a niche premium segment into a foundational hardware architecture for modern computing. As form factors continue to blur the boundaries between productivity, creativity, and mobile workflows, enterprise buyers, channel partners, and OEM strategists require more than surface-level trend summaries. They need structured, forward-looking intelligence that connects macroeconomic trajectories, component-level disruptions, and competitive maneuvering into actionable decision frameworks. PW Consulting's latest market research on the 2-in-1 Laptops Market is built precisely for that purpose: to convert complex industry signals into clear strategic direction for 2026 and beyond.
The Strategic Imperative of a Data-Backed Market View
Over the past half-decade, the category has demonstrated consistent expansion, moving from a baseline of approximately 2,590 million USD in 2020 to an estimated 3,340 million USD in 2025. That progression reflects more than incremental demand; it signals a structural shift in how organizations and individual users evaluate device versatility, input flexibility, and display interactivity. The forecast window extending through 2032 projects a compound annual growth rate of 7.0 percent, with market valuation anticipated to reach roughly 5,357 million USD by the end of the period. These figures are not abstract statistics. They represent the scale of capital allocation, product roadmap prioritization, and regional capacity planning that stakeholders must address in the current planning cycle.
For executives evaluating portfolio investments, inventory commitments, or channel strategies, the key question is no longer whether the 2-in-1 category will continue to expand, but how growth will be distributed across architectures, use cases, and supply ecosystems. A 7.0 percent CAGR in a mature hardware segment suggests sustained transition rather than speculative hype. It implies that convertible and detachable designs are becoming default considerations in specific procurement segments, while also rewarding manufacturers that can align processor roadmaps, display technologies, and service models with evolving user expectations. PW Consulting's research translates this trajectory into a structured lens for scenario planning, allowing decision-makers to test assumptions against validated historical patterns and forward projections.
Report Architecture: From Macro Trajectory to Operational Readiness
The research is organized to support both strategic oversight and tactical execution. Rather than presenting a single narrative arc, the report decomposes the market into analyzable layers that reflect how real organizations make hardware decisions. The foundation rests on historical tracking from 2020 through the 2025 base year, followed by a forecast horizon spanning 2026 to 2032. This dual structure enables readers to benchmark recent performance, identify inflection points, and calibrate medium-term expectations with confidence.
Beyond top-line sizing, the report examines the architecture split between convertible and detachable designs, mapping how each form factor addresses distinct usage profiles, thermal constraints, and input preferences. It also assesses demand patterns across consumer and commercial environments, highlighting where procurement cycles, total cost of ownership calculations, and device longevity requirements diverge. Regional coverage is integrated as a strategic layer rather than a static table, allowing readers to understand how localized purchasing behavior, distribution maturity, and policy environments shape deployment velocity.
The analytical framework further incorporates competitive positioning, supply chain sensitivity, and technology adoption timing. Readers will find structured evaluations of product line breadth, feature differentiation, and go-to-market emphasis across leading manufacturers. Equally important, the report connects these commercial signals to upstream realities such as display and touch integration, semiconductor sourcing pressures, and tariff-driven cost dynamics. The objective is to give strategists a complete operating picture: what is selling, why it is selling, where production risk is accumulating, and which capabilities are most likely to determine market share in the next planning cycle.
Competitive Landscape: Architectural Diversification and AI-Enabled Positioning
The 2-in-1 laptop arena is defined by a concentrated group of established OEMs that are competing simultaneously on hardware versatility, display quality, processor integration, and software-enabled productivity. Market concentration remains high, with the top firms collectively commanding a substantial share of category revenue. This concentration does not imply stagnation. Instead, it reflects an intense competition over micro-differentiation: hinge engineering, touch and pen responsiveness, battery endurance, screen resolution and color accuracy, and increasingly, the integration of AI-centric processing capabilities.
Dell continues to maintain a broad convertible portfolio across mainstream and performance-oriented segments, pairing touch and pen-ready configurations with current-generation Intel Core Ultra platforms. Its lineup illustrates a pragmatic approach to the category: multiple screen sizes and price tiers, consistent enterprise serviceability, and clear positioning for users who need convertible flexibility without abandoning traditional laptop ergonomics.
HP has emphasized the intersection of manageability, display quality, and AI features, particularly in business-facing convertible lines. By combining OLED touchscreen options with AI-forward branding and enterprise-grade chassis design, HP targets procurement teams that want device versatility alongside security, manageability, and visual quality for presentation-heavy or content-review workflows.
ASUS has pursued a more segmented strategy, spanning creative-oriented convertibles, lightweight gaming-capable flip systems, business flip models, and Chromebook options. The breadth of its portfolio reflects a deliberate effort to capture different purchase motivations under one roof, from color-accurate displays for professional creators to 360-degree hinge designs for education and general productivity environments.
2-In-1 Laptops Market
Acer's presence in the category highlights value-conscious engineering and, more recently, a focus on next-generation processor platforms. Its convertible offerings span budget-friendly spin designs, business travel models, and AI-branded flip systems. This range demonstrates how aggressively the category is being extended into multiple price and performance bands, making 2-in-1 configurations accessible to a wider set of buyers.
Lenovo has leaned into the convergence of design refinement, OLED touchscreen adoption, and AI PC narratives. Its convertible and detachable-oriented lines target both premium consumer segments and commercial buyers seeking balanced ergonomics and modern input experiences. The emphasis on Copilot+ features and OLED implementation shows how manufacturers are using software and display quality as leverage in a category where hardware form factors are increasingly familiar to consumers.
Samsung has positioned its Galaxy Book 360 lineup around high-end display technology and integrated ecosystem appeal. With Super AMOLED touchscreens and Intel Core Ultra platforms, these devices reinforce the idea that 2-in-1 devices can serve as premium productivity and media tools rather than merely compromise form factors. The strategy aligns with a broader push toward visually rich, AI-capable devices that perform well in both tablet and laptop modes.
Microsoft remains a defining presence through its Surface line, particularly with detachable-oriented devices powered by advanced silicon options. Its high-end detachable offerings underscore the enduring relevance of detachables in scenarios where tablet-first usage, portability, and pen-based interaction take priority. At the same time, the broader competitive conversation shows that detachable and convertible designs are not interchangeable; each serves distinct workflow assumptions and purchase criteria.
Taken together, these players reveal a market where success depends less on announcing a new form factor and more on executing consistently across display quality, battery performance, thermal management, support ecosystems, and supply reliability. PW Consulting's research evaluates these competitive signals in a way that helps stakeholders identify where differentiation is genuine and where product narratives risk blending into commodity positioning.
Industry Dynamics: Supply Chain Realignment, Component Innovation, and Tariff-Driven Economics
The category's growth trajectory is unfolding against a backdrop of meaningful operational friction. Recent sector analysis points to tariff-related pressures and export restrictions affecting advanced semiconductor components, prompting manufacturers to diversify sourcing and accelerate localization strategies. These developments are not incremental conveniences; they reshape cost structures, lead-time expectations, and regional production planning. For 2-in-1 laptops, which depend on integrated display, touch, and processing ecosystems, any disruption in component availability can cascade quickly into product timing and margin performance.
Tariff actions and retaliatory measures from trade partners have added further complexity by raising production costs for consumer goods, including 2-in-1 laptops, with estimates indicating cost increases in a broad double-digit range. Alongside that, supply chain disruptions have become a recurring risk factor rather than an occasional exception. Semiconductor and display sourcing remain especially sensitive, and the U.S. General Services Administration has noted that such disruptions have translated into longer lead times and higher costs for critical laptop components. In a category where hinge design, touch integration, and thin-chassis thermal constraints already demand precise component coordination, these pressures can influence everything from bill-of-material planning to channel inventory strategy.
Gaming Laptop Market
Despite these headwinds, component-level innovation continues to open differentiation opportunities. Himax Technologies' move into mass production of OLED Touch IC for IT applications is a notable example. By enhancing integrated display and touch performance with industry-leading characteristics, such component advances can improve the user experience that manufacturers rely on to justify premium pricing and reinforce product identity. At the device level, recent introductions such as AI-focused convertible systems powered by next-generation Snapdragon platforms illustrate how manufacturers are translating NPU capability, extended battery life, and multi-monitor support into tangible value propositions. These product developments matter because they show that the category is still evolving in ways that go beyond hinge rotation or screen size alone.
For strategic planners, the implication is clear: market expansion is real, but it is being filtered through a more complicated operating environment. Revenue opportunity must be weighed against sourcing resilience, tariff exposure, logistics risk, and the cost of localizing or dual-sourcing critical inputs. PW Consulting's report addresses these tensions directly, giving readers a structured way to evaluate where demand is durable and where execution risk may erode expected returns.
Why This Research Matters for 2026 Decision-Making
In 2026, hardware strategy is no longer about forecasting a single growth curve. It is about aligning product mix, channel behavior, procurement expectations, and supply chain options within a market that is simultaneously expanding and fragmenting in its competitive logic. The 2-in-1 laptop category exemplifies this challenge. It offers clear long-term demand support, yet it also requires careful interpretation of form-factor preferences, commercial versus consumer buying patterns, regional purchasing conditions, and component-level constraints.
This research is designed to reduce uncertainty at exactly those decision points. It provides a disciplined framework for interpreting historical performance, evaluating forward projections, and understanding how competitive and operational variables interact. Readers gain clarity on where the market is heading in aggregate, how major players are positioning themselves, and which structural pressures are most likely to influence cost, availability, and differentiation in the near term. Just as importantly, the report is built to support internal discussion: it gives product leaders, procurement teams, channel strategists, and investors a common reference point for debating scenario outcomes and prioritizing investments.
The full study goes further than the overview presented here. It contains the detailed segmentation logic, competitive profiles, regional interpretations, and operational risk analysis needed to convert high-level market direction into executable plans. To access the complete dataset, segmentation breakdowns, and strategic recommendations underpinning this analysis, visit the source report page and obtain the full intelligence package. In a market where timing, positioning, and supply resilience determine competitive outcomes, that deeper view is the difference between reactive planning and confident strategic action.
For detailed analysis of this topic, please visit the official page: 2-In-1 Laptops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The revenue trajectory of the global high voltage power cables market shows sustained and accelerating growth from 2020 to 2035, driven by electrification trends, grid upgrades, and expanding renewable projects. In 2025, the market is estimated at USD 42,500 million, with projections to surpass USD 84,700 million by 2035, indicating a robust CAGR. This growth reflects both replacement demand in mature economies and extensive new installations in emerging markets, underscoring the sector's centrality to global energy transition.
Read More - https://bussinessinsights.com/research-report/global-high-voltage-power-cables
By applications, power transmission constitutes the largest portion of the high voltage power cables market in 2025, as utilities and grid operators modernize networks to accommodate rising energy demands and renewable integration. Power distribution accounts for the next significant share, driven by urban grid expansions. Renewable energy and industrial applications are both rapidly increasing their share, reflecting broader sustainability trends and large-scale industrial electrification. The diversity of applications underlines the strategic role of HV cables in supporting resilient, efficient, and sustainable electricity networks across regions.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-high-voltage-power-cables
Frequently Asked Questions
Who are the key players in Global High Voltage Power Cables industry?
The top 5 players in the Global High Voltage Power Cables market include Prysmian Group, Nexans, Sumitomo Electric, NKT A/S, and LS Cable & System. These companies are major manufacturers, offering advanced cable solutions worldwide and driving technological innovation, extensive distribution, and expansion to meet rising electricity demand.
What is the Global High Voltage Power Cables growth?
The Global High Voltage Power Cables market has experienced steady growth, driven by increasing investments in grid expansion and renewable energy projects. For example, Nexans recently secured major contracts to supply high voltage cables for offshore wind projects, reflecting the industry’s strong momentum in sustainable infrastructure development.
Which segment accounted for the largest Global High Voltage Power Cables share?
Power transmission and distribution applications hold the largest share in the Global High Voltage Power Cables market. Expanding urbanization and the integration of renewables into the grid have increased demand for reliable, efficient cables for utility-scale transmission, especially in emerging economies and developed regions updating aging infrastructure.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The market revenue for nitrogen oxides analyzers is projected to climb steadily from 2020 to 2035. In 2025, global revenue is estimated at USD 1,160 Million, reflecting a compound annual growth rate (CAGR) of roughly 8.5% from 2025 to 2035. This consistent growth is driven by intensifying regulatory pressures and technological advancements that enhance product reliability, accuracy, and integration with digital monitoring platforms. By 2030, the market is expected to surpass USD 1,750 Million, exceeding USD 2,500 Million by 2035, indicating robust demand and ongoing innovation across industrial and environmental monitoring sectors.
Read More - https://bussinessinsights.com/research-report/global-nitrogen-oxides-analyzers
Industrial emissions remain the leading application for nitrogen oxides analyzers in 2025, accounting for 37% of the total market share. The industrial sector's need for continuous emission tracking and compliance with rigorous regulations highlights the segment's significance. Environmental monitoring and the automotive sector follow with 27% and 18% share respectively, reflecting increased global efforts to manage urban air quality and reduce vehicular emissions. Power generation and chemical industry applications collectively represent another 18%, underscoring the critical role of NOx monitoring in process-driven environments.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-nitrogen-oxides-analyzers
Frequently Asked Questions
Who are the key players in Global Nitrogen Oxides Analyzers industry?
The top five players in the global nitrogen oxides analyzers market are Thermo Fisher Scientific, HORIBA, Siemens, Teledyne Technologies, and Ecotech. These companies are recognized for their advanced technology, strong global presence, and comprehensive product portfolios catering to both industrial and environmental monitoring applications.
What is the Global Nitrogen Oxides Analyzers growth?
The global nitrogen oxides analyzers market has seen steady growth, driven by strict emission regulations. For example, Thermo Fisher Scientific recorded increased demand in 2023 due to heightened environmental monitoring in North America and Europe, boosting the overall market growth and technology adoption.
Which segment accounted for the largest Global Nitrogen Oxides Analyzers share?
The industrial emissions monitoring segment held the largest share in the global nitrogen oxides analyzers market. Industries such as power generation, oil & gas, and chemicals rely on these analyzers to comply with emissions standards, with stringent regulatory frameworks fueling widespread adoption across these applications.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global printing for packaging market is forecasted to expand from USD 150,000 million in 2025 to USD 230,000 million by 2035, reflecting increased consumer goods production, e-commerce proliferation, and advancing print technologies. The market displays a steady CAGR driven by ongoing investments in digitalization and eco-friendly packaging. Notable upticks in demand are seen post-2025 as companies ramp up adoption of smart, sustainable printing solutions, responding to regulatory shifts and evolving consumer preferences worldwide.
Read More - https://bussinessinsights.com/research-report/global-printing-for-packaging
The food & beverage segment dominates application share in the printing for packaging market in 2025, owing to stringent branding, regulatory, and safety demands. Pharmaceuticals represent the next largest segment, emphasized by traceability and security packaging requirements. Personal care & cosmetics stand out for their emphasis on premium and visually appealing packaging. Household products, electronics, and others collectively make up the remainder, with trends driven by functional, aesthetic, and regulatory concerns. This segmentation underscores the critical role of packaging in brand differentiation, compliance, and consumer appeal across multiple verticals.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-printing-for-packaging
Frequently Asked Questions
Who are the key players in Global Printing For Packaging industry?
The top five key players in the Global Printing For Packaging industry are Amcor plc, WestRock Company, Sonoco Products Company, Mondi Group, and Quad/Graphics, Inc. These companies are recognized for their innovative printing solutions, extensive global presence, and strong focus on sustainable packaging and advanced print technologies.
What is the Global Printing For Packaging growth?
The Global Printing For Packaging market has shown robust growth, driven by rising demand for consumer goods and e-commerce. In 2023, Amcor plc reported a strong increase in flexographic packaging, and the sector is projected to grow at a CAGR of over 5% through 2030, as sustainability solutions gain traction.
Which segment accounted for the largest Global Printing For Packaging share?
The food and beverages sector holds the largest share in Global Printing For Packaging. With increasing demand for packaged food products and innovative branding, this application dominates the market. Companies like WestRock and Mondi are leaders in delivering advanced, customized food packaging print solutions worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Between 2020 and 2035, the global sailboat propellers market is expected to register consistent growth, rising from USD 582 Million in 2020 to an estimated USD 1,146 Million by 2035. The period between 2025 and 2030 will see the sharpest revenue growth, as innovation, expanding applications, and wider adoption in emerging regions drive higher sales volumes and value.
Read More - https://bussinessinsights.com/research-report/global-sailboat-propellers
Leisure application leads the sailboat propellers market in 2025, accounting for a significant portion due to rising yacht ownership and recreational sailing enthusiasm. Racing and commercial applications also mark substantial shares, benefiting from technology upgrades and increased participation in competitive events. Defense and rescue/patrol applications are niche but growing, fueled by demand for high-performance and custom solutions.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-sailboat-propellers
Frequently Asked Questions
Who are the key players in Global Sailboat Propellers industry?
Major players in the global sailboat propellers market include Bruntons Propellers, EWOL Propellers, Gori Propeller, Flexofold ApS, and Michigan Wheel. These companies are renowned for their technological innovation, high-quality manufacturing, and strategic partnerships, making them leaders in sustainable and efficient marine propulsion solutions worldwide.
What is the Global Sailboat Propellers growth?
The global sailboat propellers market has witnessed steady growth, with increased demand largely fueled by boating tourism and a rising interest in recreational sailing. Companies like Flexofold reported strong order volume and product innovation in 2023, signaling positive momentum in the sector.
Which segment accounted for the largest Global Sailboat Propellers share?
Recreational sailing applications accounted for the largest market share. The popularity of leisure boating activities, particularly in North America and Europe, has pushed demand for high-performance and environmentally friendly propeller solutions tailored to cruising and racing sailboats.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting Reports 5.55% CAGR for Progressing Cavity Pumps Market to Reach $2,036.03 Million by 2032
By PW Consulting, 2026-09-16
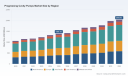
Navigating the Future of Fluid Handling: Strategic Insights from the Progressing Cavity Pumps Market Forecast 2026-2032
The global industrial landscape is undergoing a profound transformation driven by efficiency demands, regulatory shifts, and the relentless need for reliable fluid management solutions. For stakeholders in the progressing cavity pump (PCP) sector, the period from 2026 through 2032 represents a critical window of opportunity and challenge. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip leadership teams with the actionable intelligence required to navigate this evolving terrain.
As enterprises finalize their strategic roadmaps for the upcoming fiscal years, understanding the macroeconomic currents shaping the PCP market is no longer optional—it is imperative. This briefing serves as an introduction to our deep-dive analysis, outlining the trajectory of market growth, the competitive dynamics at play, and the operational variables that will define profitability in the years ahead. While this article provides a high-level overview of the strategic landscape, the full report contains the granular segmentation and proprietary data necessary for precise capital allocation and market entry strategies.
Market Trajectory and Growth Horizons
The progressing cavity pump market has demonstrated resilience and steady expansion over the past half-decade. Our analysis tracks performance from 2020 through the base year of 2025, providing a robust historical foundation for forecasting future trends. The market has grown consistently, driven by increased industrialization and the expanding application of PCP technology in demanding environments ranging from heavy oil extraction to precise food processing.
Looking toward the forecast period of 2026 to 2032, the momentum is expected to continue. The market is projected to reach significant revenue milestones by the end of the forecast window. This growth is not merely a function of inflation but reflects genuine adoption rates and technological modernization across key sectors. The compound annual growth rate (CAGR) indicates a steady upward trajectory, suggesting that demand for specialized fluid handling equipment will outpace broader industrial sluggishness in certain segments.
For strategic planners, these figures underscore the importance of timing. Entering or expanding within this market requires alignment with the growth curves identified in our study. The data suggests that while the early years of the forecast period may see moderate expansion, the later years present accelerated opportunities as infrastructure projects mature and new technologies gain widespread acceptance. Understanding the inflection points in this revenue curve is essential for optimizing inventory, production capacity, and investment timelines.
Segmentation Dynamics and Operational Drivers
The versatility of progressing cavity pumps is reflected in their diverse deployment across various configurations and end-use industries. Our research dissects the market into critical dimensions, including pump type and application sector. This segmentation is vital because growth is not uniform across all categories. Some configurations are experiencing faster adoption due to specific industry trends, such as the shift toward more efficient artificial lift methods in oilfields or the increasing stringent hygiene standards in food processing.
-
Technological Configurations
The market is categorized by stage configurations, each serving distinct performance requirements. Single-stage, double-stage, and four-stage pumps cater to different pressure and viscosity needs. Our analysis reveals how the balance among these configurations is shifting. For instance, higher-stage configurations may see increased demand in applications requiring greater head pressure, while single-stage units remain vital for specific low-pressure, high-flow scenarios. The choice of configuration directly impacts maintenance schedules and operational expenditure, making this segment analysis crucial for product portfolio planning.
-
Industry Applications
End-user application is a primary driver of demand. Key sectors include Oil and Gas, Water and Wastewater, Chemical and Petrochemical, Food and Beverage, and Others. Each sector presents unique challenges and regulatory requirements. The Oil and Gas sector continues to be a major contributor, particularly in artificial lift solutions where reliability in harsh downhole conditions is paramount. Simultaneously, the Water and Wastewater sector is gaining traction due to environmental regulations and the need for handling abrasive slurries and viscous fluids without degradation.
The Food and Beverage industry represents a high-growth niche where hygienic designs compliant with international standards are non-negotiable. Chemical processing also remains a steadfast consumer of PCP technology, driven by the need to handle shear-sensitive materials. Our report details the revenue contributions and growth rates of each application area, helping clients identify which verticals offer the highest return on investment for their specific capabilities.
Competitive Landscape and Strategic Positioning
The global PCP market is characterized by a mix of specialized manufacturers and diversified industrial giants. Market concentration metrics indicate a moderate level of consolidation, with the top three players holding a significant share, though ample room remains for niche competitors and regional specialists. Understanding the competitive hierarchy is essential for benchmarking performance and identifying partnership or acquisition opportunities.
Process Gas Compressor Market
Key Market Participants
Several companies define the current competitive landscape, each bringing distinct strengths to the table:
- PCM Group (France): A leader in progressing cavity pumps with a global presence in over 90 countries. Their portfolio includes the EcoMoineau MX, HyCare, and Moineau A series. Recent activities highlight their focus on oily water treatment and hygienic meat transfer solutions, showcasing adaptability across industrial and sanitary applications.
- NETZSCH Pumps & Systems (Germany): Recognized as a global leader in NEMO progressing cavity pumps. They serve chemical, environmental, mining, and oil and gas sectors. Recent innovations focus on hermetic seal upgrades that allow safer handling of toxic liquids without maintenance, addressing critical safety regulations.
- SEEPEX (Germany): A specialist in standard progressive cavity pumps, hopper pumps, and API 676 models. They are notable for integrating digital control systems, catering to abrasive, shear-sensitive, and viscous fluids across multiple industries.
- NOV Process & Flow Technologies (United States): Providers of Mono and Moyno technologies. Their emphasis lies in oilfield artificial lift, heavy oil, and high-sand applications, positioning them strongly within the energy extraction segment.
- Weatherford International (United States): Suppliers of PCP systems and artificial lift solutions tailored for oil and gas wells. They offer material options designed to withstand harsh downhole conditions, competing directly in the upstream energy space.
- ChampionX Corporation (United States): Developers of PCP pumping systems including SMARTEN VSD and HiCone models. Their focus is heavily oriented toward oilfield applications and artificial lift technologies.
- Sulzer Ltd (Switzerland): Providers of progressing cavity pump solutions for chemical processing, energy, and industrial sectors, leveraging a broad engineering heritage.
- Roto Pumps Limited (India): Manufacturers of high-pressure progressive cavity pumps for chemical, mining, wastewater, and power plant applications, representing strong growth potential in emerging markets.
- ITT Bornemann GmbH (Germany): Suppliers of Bornemann progressing cavity pumps focused on hygienic, sanitary, and industrial fluid handling, competing in the high-sanitation niche.
- Nova Rotors Srl (Italy): Producers of Diamond progressing cavity pumps and related grinders. Recent participation in food and beverage exhibitions underscores their commitment to this sector.
- Flexon-All Srl (Romania): Manufacturers of custom progressive cavity pumps with 22 standard types, offering flexibility for flows ranging from 1.6 to 135 m³/day.
Beyond the established giants, the landscape includes regional players who compete on customization and cost-efficiency. Strategic decisions regarding partnerships or market entry must consider the specific strengths of these competitors, such as NETZSCH's recent advancements in hermetic seals or PCM's focus on reducing maintenance downtime through maintenance-in-place designs.
Industry Dynamics and Risk Factors
No strategic plan is complete without a thorough assessment of the external forces that could impact operations. Our report integrates several critical dynamics that are currently shaping the PCP market environment. These factors influence not only the cost of goods sold but also the regulatory compliance burden and the overall value proposition offered to customers.
Supply Chain and Material Volatility
One of the most significant challenges facing manufacturers is the volatility of raw materials. The elastomer raw materials and specialized polymers used in stators are subject to price swings that can impact the bottom line. Industry data suggests these fluctuations can cause annual price variations touching double digits. Since stator costs can form a significant portion of the total pump value, even minor changes in material pricing can ripple through to final equipment costs. Furthermore, quarterly fluctuations of up to 15% in elastomeric stator materials have been observed due to supply chain factors. Effective procurement strategies and supplier diversification are therefore critical competencies for maintaining margin stability.
Regulatory and Safety Standards
Regulatory pressure is mounting, particularly regarding safety and hygiene. New hermetic seal upgrades for progressing cavity pumps are enabling safer handling of toxic liquids and gases without the need for frequent maintenance. This innovation aligns with stricter occupational health and safety regulations in chemical and energy sectors. Additionally, in the food and beverage sector, hygienic and sanitary progressing cavity pumps must comply with EHEDG and FDA standards. Compliance is not just a legal requirement but a competitive differentiator. Companies that fail to adapt to these standards risk losing access to high-value market segments.
Operational Efficiency and Labor Costs
Labor costs and downtime are persistent concerns for operators. Maintenance-in-place designs, such as those highlighted by PCM Group, reduce pump removal downtime and associated labor requirements. In an environment where skilled labor is increasingly scarce and expensive, equipment that minimizes intervention offers a compelling economic advantage. This trend is driving purchasing decisions toward technologies that promise longer service intervals and easier onsite maintenance. Strategic planners must weigh the initial capital expenditure against these long-term operational savings when evaluating market opportunities.
Strategic Implications for 2026 Decision Makers
As organizations move into 2026, the insights derived from this market research will inform several key strategic pillars. First, market entry and expansion decisions must be data-driven. Knowing which regions and applications are growing fastest allows for targeted marketing and distribution efforts. Second, product development roadmaps should align with the shifting demand between single-stage, double-stage, and four-stage configurations, as well as the increasing integration of digital controls and hermetic seals.
Progressing Cavity Pumps Market
Third, risk management strategies need to account for raw material volatility. Hedging strategies or long-term supply contracts may become necessary to protect margins. Finally, M&A activity remains a viable path for consolidation. With a moderate concentration level, there is potential for acquiring niche players to gain access to specific regional markets or application expertise, such as the hygienic food processing sector or high-sand oilfield applications.
Conclusion and Access to Full Intelligence
The Progressing Cavity Pumps Market is poised for steady growth, underpinned by industrial expansion and technological innovation. However, realizing value in this market requires more than a superficial understanding of global totals. It demands a deep grasp of segmentation shifts, competitive maneuvers, and the nuanced dynamics of supply chains and regulations.
This article has outlined the strategic framework and high-level trends defining the sector. Yet, the full depth of our analysis contains the specific segmentation data, regional breakdowns, and detailed company profiles necessary to build a robust business case. The complete report offers the granular intelligence required to validate assumptions and finalize investment decisions with confidence.
For executives and analysts seeking to secure a competitive advantage in the 2026-2032 period, PW Consulting's full market research report provides the essential toolkit. We invite you to access the complete study to unlock the detailed forecasts, segmentation splits, and strategic recommendations that will drive your organization's success in the evolving landscape of progressing cavity pump technology.
For detailed analysis of this topic, please visit the official page: Progressing Cavity Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
BOE International 2027 is an important meeting point for professionals from the event and exhibition industry. If your company is planning to exhibit at the show, a well-designed exhibition stand can help create a strong brand presence and provide a professional space for meetings, demonstrations, and networking.
The next BOE International will take place on January 20–21, 2027, at Messe Dortmund, Germany . The official opening hours are 10:00 AM–6:00 PM on January 20 and 10:00 AM–5:00 PM on January 21.
Professional Exhibition Stand Builder for BOE International 2027
Choosing an experienced Exhibition Stand Builder for BOE International can make the preparation of your trade show presence easier. From the first design concept to installation at Messe Dortmund, every part of the booth needs careful planning.
Castle Booth Builder provides exhibition stand design and construction solutions based on your brand, available space, products, and objectives. The team can create custom exhibition stands that combine practical functionality with an attractive visual presentation.
Whether you need a small booth for focused meetings or a larger custom stand for product demonstrations, the design can be planned around your requirements.
BOE International 2027 – Event Details
BOE International is focused on the event industry and brings together areas including Event & Exhibition Construction, Event Equipment, EventTech & AV, Event IT, Event Marketing & Promotion, Entertainment, Locations & Acts, and Catering .
Event: BOE International 2027
Date: January 20–21, 2027
Venue: Messe Dortmund
Location: Rheinlanddamm 200, 44139 Dortmund, Germany
Industry: Event and exhibition industry
Opening Hours:
- January 20: 10:00 AM–6:00 PM
- January 21: 10:00 AM–5:00 PM
The official exhibitor information states that stand construction is scheduled for January 16–19, 2027 , while dismantling starts on January 21 after the exhibition closes and ends on January 22, 2027.
Custom Booth Design for BOE International
A custom exhibition stand can give your company a dedicated space to present its products and services. For BOE International, the booth can be planned with product displays, meeting areas, reception counters, storage, graphics, lighting, and presentation areas.
A good booth design should also consider visitor movement. Clear branding, accessible meeting spaces, and well-positioned displays can make the stand easier for visitors to explore.
Castle Booth Builder can develop custom booth design, 3D booth concepts, exhibition stand construction, graphics, furniture, installation, and dismantling according to the project requirements.
Exhibition Stand Construction in Dortmund
Working with an exhibition stand builder in Dortmund can simplify the logistics involved in preparing for BOE International. The official event information provides specific build-up and dismantling periods, so exhibition stand construction needs to be coordinated around the venue schedule.
Castle Booth Builder can coordinate the different stages of the project, including:
- Exhibition stand design
- 3D booth visualization
- Custom booth construction
- Modular exhibition stands
- Exhibition graphics and branding
- Furniture and lighting
- Stand installation
- Dismantling
- Logistics coordination
- Project management
Why Plan Your BOE International Stand Early?
Planning your booth early gives your team more time to finalize the design, graphics, furniture, technical requirements, and logistics. The official BOE International exhibitor information also notes that late orders for stand construction, furniture, and other services can be subject to additional charges from six weeks before the trade fair.
For this reason, exhibitors can benefit from starting the BOE International 2027 exhibition stand design well before the event.
Create a Strong Brand Presence at BOE International 2027
Your exhibition stand is more than a physical structure. It is a space where visitors can discover your brand, discuss your solutions, and meet your team.
A professional trade show booth builder for BOE International can help turn your available floor space into a practical and attractive exhibition environment. From concept development to final installation, each stage can be coordinated to create a consistent brand experience.
If you are exhibiting at BOE International 2027 in Dortmund , Castle Booth Builder can help with your complete exhibition stand project. Whether you are looking for a custom exhibition stand builder, booth design company, exhibition stand contractor, or trade show booth construction service , the project can be planned around your brand and exhibition requirements.
Start planning your Exhibition Stand for BOE International 2027 early and prepare your booth for January 20–21, 2027, at Messe Dortmund.